Crops, equipment, irrigation, livestock — with repayment aligned to harvest, not to a bank's month-end.
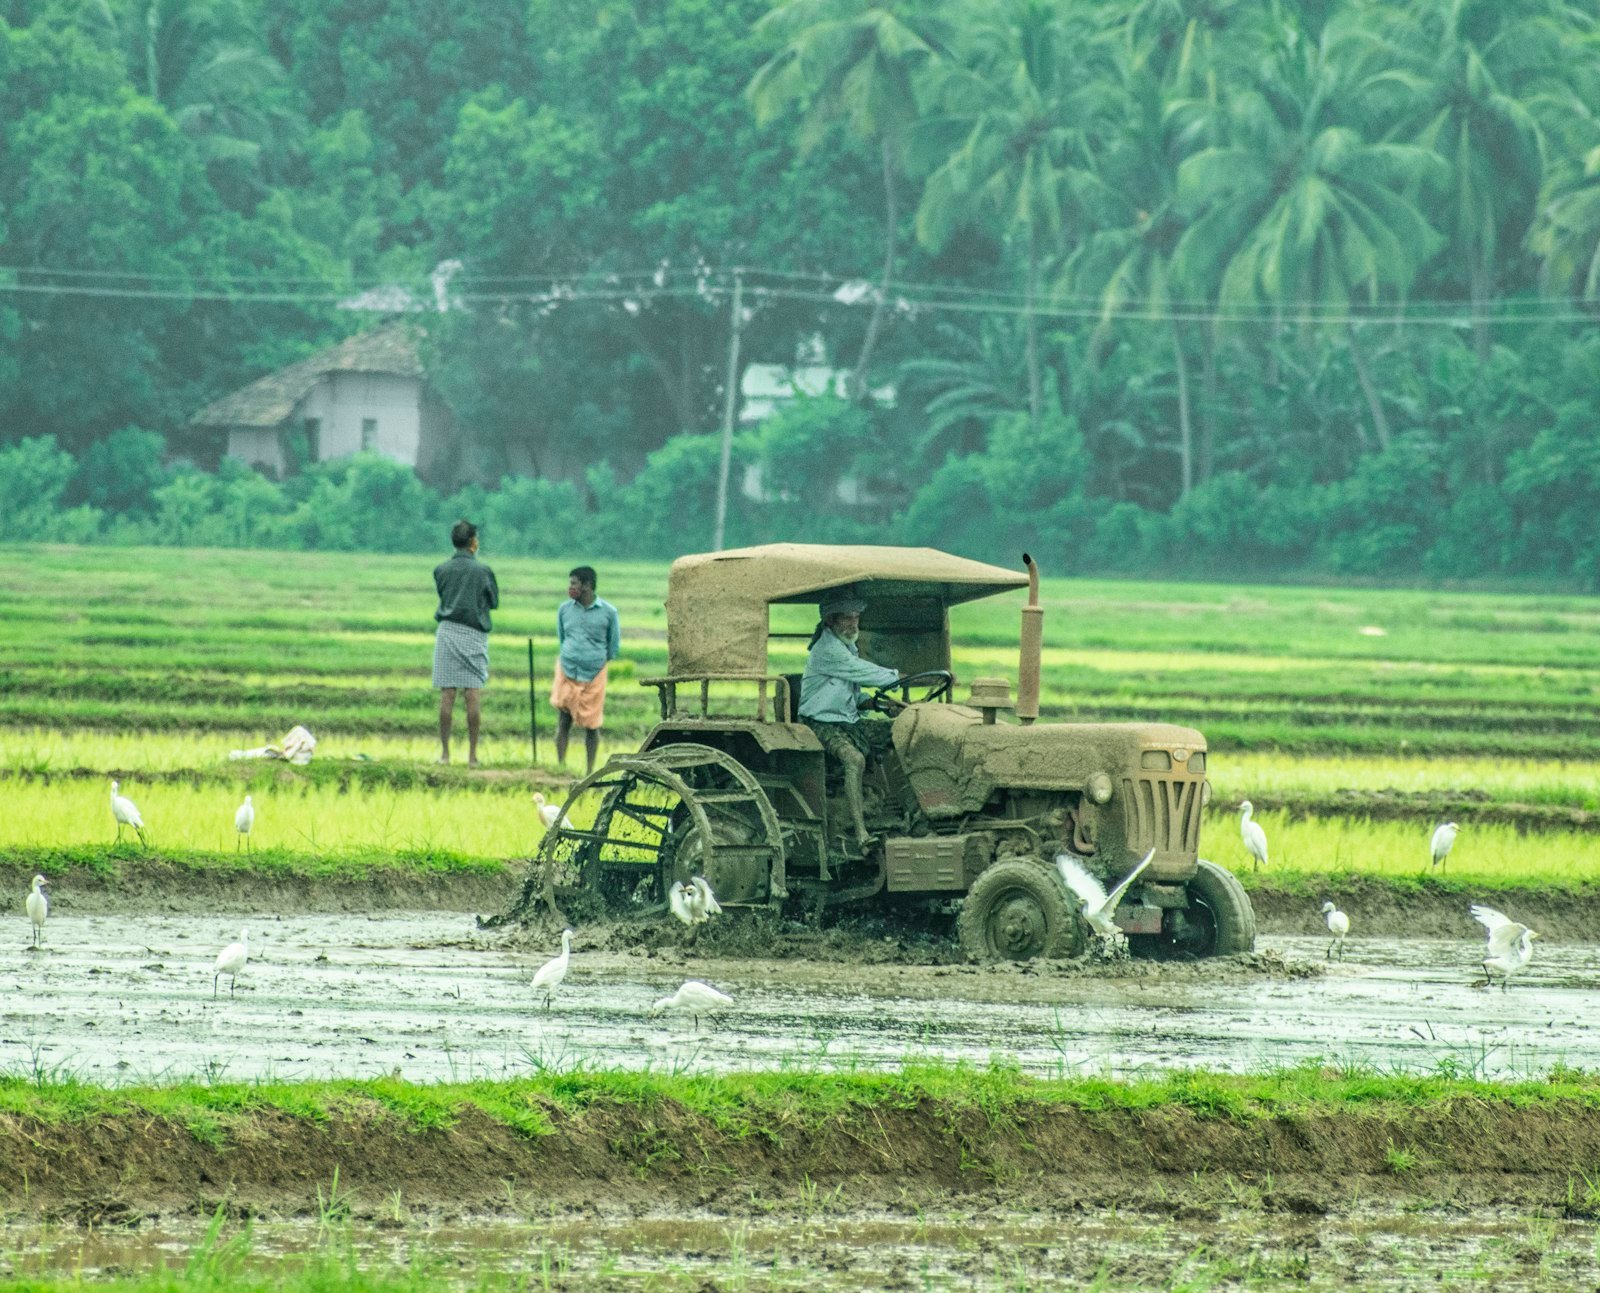 Illustrative photograph
Farming income does not arrive in twelve equal instalments, so farm credit should not demand them. We structure agriculture loans around the sowing and harvest cycle, for farmers, agribusinesses and rural entrepreneurs alike.
Repayment scheduled around the agricultural cycle.
Built for the cycle
Repayment lands after the harvest, not in the middle of the growing season.
Affordable rates
Priced to keep the repayment burden proportionate to what the land earns.
Fast when it matters
Seasonal windows are short. Approvals and disbursal are built to match.
Minimal documentation
A short, practical document list — nothing that needs a city trip to collect.
One product name, several different structures. We will point you at the one that costs you least.
Crop loans
Seeds, fertiliser and pesticide for a healthy harvest.
Farm equipment loans
Buy or upgrade tractors, harvesters and implements.
Agri infrastructure loans
Irrigation, storage, cold chain and farm development.
Dairy & livestock loans
Expand herds, cover feed and veterinary costs.
Horticulture loans
Fruit, vegetable and greenhouse cultivation.
Organic farming loans
Organic inputs and the certification that pays for itself.
Individual farmers, SHGs, JLGs, partnerships and agri businesses
Proof of land ownership or a registered lease
KYC documents in order
A reasonable repayment record
Not sure you qualify?
Checking does not affect your credit score and does not commit you to anything. Send your details and we will tell you honestly where you stand.
Check eligibilityCollect these once and the rest moves quickly. Missing paperwork is the single biggest cause of delay on any loan file.
Proof of identity
- Aadhaar Card
- PAN Card
- Passport
- Voter ID
- Driving Licence
Proof of address
- Aadhaar Card
- Utility bill (electricity, water, gas)
- Passport
- Voter ID
- Registered rent agreement
Land & farming papers
- Land ownership records or registered lease deed
- Khasra / khatauni extracts
- Cropping pattern and acreage details
- Farm business plan for larger facilities
Income proof
- Latest salary slips (last 3 months)
- Bank statements (last 6 months)
- Form 16 or ITR (last 2 years)
- Income tax returns (last 2 years)
- Audited financials, where applicable
Projections, for larger loans
- Expected crop yield
- Input costs and expenses
- Profit and cash flow estimate
Move the sliders. This is the same reducing-balance formula every lender uses, so the figure you see here is the figure you should expect on a sanction letter at that rate.
A shorter tenure shrinks the teal slice fast.
- Principal
- ₹12,00,000
- Total interest
- ₹3,47,561
- Total payable
- ₹15,47,561
An estimate. Your sanctioned rate depends on your credit profile, income and the lender. Processing fees and insurance are not included above.